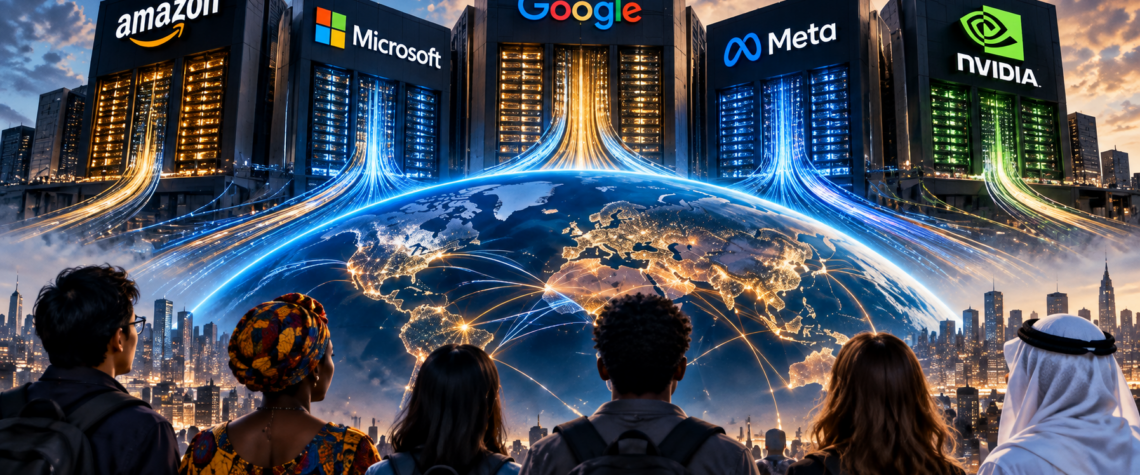
Artificial intelligence promises to democratize knowledge and opportunity. But the chips, data centers, computing infrastructure, and financial resources behind it are increasingly concentrated in the hands of a small number of corporations.
Artificial intelligence is often described as the great democratizing technology of our time. Anyone with an internet connection can ask a question, write computer code, translate a document, or explore ideas that once required specialized knowledge. But behind this apparent accessibility lies a striking paradox. While millions of people can use artificial intelligence, relatively few companies control the infrastructure required to develop and operate its most powerful systems.
The computers that train advanced AI models cost enormous sums. The specialized chips that power them are produced through a tightly concentrated industrial supply chain. The cloud services that make these technologies available are dominated by a handful of corporations with the financial resources to build vast networks of data centers. The result is a new concentration of economic and technological power whose consequences may extend far beyond the technology industry. Who owns the intelligence that increasingly shapes our lives? And who will decide how its benefits are distributed?
The Invisible Infrastructure Behind AI
When someone opens an AI application on a smartphone, the experience appears almost effortless. A question is entered, and an answer appears seconds later. But the response may depend on thousands of specialized processors operating in distant data centers, connected through sophisticated networks and consuming substantial amounts of electricity.
Building this infrastructure requires access to advanced semiconductors, reliable power supplies, engineering expertise, and extraordinary amounts of capital. These requirements create formidable barriers for new competitors. A small startup may develop an innovative AI application, but training a model at the technological frontier is a different undertaking. It requires resources that only a limited number of companies, research institutions, and governments can currently assemble.
According to research published by Epoch AI, five major technology companies—Amazon, Google, Meta, Microsoft, and Oracle—collectively controlled an estimated 71 percent of global AI computing capacity measured in H100-equivalent processors by the fourth quarter of 2025. The figure is an estimate based on tracked chip acquisitions rather than a complete census of every computing system. Nevertheless, it illustrates how concentrated this essential resource has become. In the AI economy, access to computing power increasingly determines who can compete.
The Companies Behind the Chips
One of the clearest examples of concentration appears in the semiconductor industry. Nvidia has become a central supplier of the advanced graphics processing units used to train and operate many AI systems. Its technology, software ecosystem, and extensive developer support have given it an exceptionally strong position. But Nvidia is only one part of a complex global supply chain.
Nvidia’s dominance is particularly striking. Industry estimates place its share of the AI accelerator market at roughly 80% or higher, depending on how the market is defined and measured. This commanding position gives the company enormous influence over the computing infrastructure powering today’s most advanced artificial intelligence systems.
Taiwan Semiconductor Manufacturing Company, or TSMC, plays a leading role in manufacturing advanced chips designed by other companies. The Dutch company ASML supplies highly specialized lithography equipment essential to leading-edge semiconductor production. According to the Organization for Economic Co-operation and Development, individual companies hold exceptionally large market shares in several critical segments of the AI infrastructure supply chain.
This concentration does not automatically mean that these businesses are acting unlawfully or preventing competition. Their positions also reflect decades of investment, technological achievement, and industrial specialization. Yet the dependence is real. When a small number of suppliers control technologies that competitors cannot easily reproduce, disruptions, shortages, or commercial decisions can affect the development of artificial intelligence worldwide.
The Cloud Giants and Their Growing Influence
Cloud computing is another critical part of the equation. Microsoft Azure, Amazon Web Services, and Google Cloud provide the infrastructure on which countless businesses, research organizations, and AI developers depend. These companies do more than rent computing capacity. They also invest in AI developers, distribute AI services, develop their own models, and integrate artificial intelligence into existing software ecosystems.
Such relationships can accelerate innovation. AI developers gain access to computing resources and financing that might otherwise be unavailable, while cloud companies gain valuable technologies and customers. But the arrangements can also create complicated dependencies.
In January 2025, the U.S. Federal Trade Commission published a report examining partnerships involving Microsoft, Amazon, Google, Open AI, and Anthropic. The agency identified potential competition concerns, including restrictions on access to computing resources, increased costs of switching providers, and the possibility that cloud companies could obtain commercially sensitive information about their AI partners.
These findings did not establish that every partnership was anticompetitive. They demonstrated why regulators are examining how ownership, investment, and infrastructure access interact. A company does not need to own every AI model to exercise considerable influence over the industry. Controlling the infrastructure on which those models depend can itself become a powerful competitive advantage.
When Innovation Depends on Permission
The concentration of computing power creates an important dilemma for smaller companies. An entrepreneur may have an original idea for an AI service but still depend on a major technology provider for the computing resources, models, distribution channels, and technical tools needed to bring it to market. This dependence is not inherently harmful. Shared cloud infrastructure has allowed countless startups to enter markets without constructing their own data centers.
However, difficulties arise when changing providers becomes expensive, competing products receive preferential treatment, or essential technologies are available only under restrictive conditions. The OECD has warned that concentration in computing infrastructure, data, and specialized expertise could create persistent barriers to competition across the AI industry.
At the same time, competition among AI model developers remains active. New models continue to appear, capabilities improve, and prices for some AI services have declined. The industry is therefore neither a single monopoly nor a perfectly open marketplace. It is a rapidly evolving ecosystem in which innovation at one level can coexist with substantial concentration at another.
The Countries Left Behind
The consequences are not limited to corporations. Artificial intelligence is becoming a strategic economic resource, much like telecommunications infrastructure, electricity, or advanced manufacturing capacity.
Countries with access to powerful computing systems, specialized researchers, and investment capital are better positioned to develop AI technologies suited to their own economic and social priorities. Countries without those resources may become dependent on systems developed elsewhere.
The United Nations Conference on Trade and Development has warned that AI research, infrastructure, and investment remain heavily concentrated in a small number of economies. Its 2025 Technology and Innovation Report found that the United States and China together accounted for approximately 60 percent of AI patents, while computing infrastructure was disproportionately located in wealthier countries. This imbalance raises difficult questions for developing nations.
Will their schools, hospitals, agricultural services, and government institutions have affordable access to AI systems? Will those systems understand local languages, cultures, and economic conditions? Or will countries be forced to adapt their needs to technologies designed primarily for wealthier markets?
The World Bank has emphasized that developing economies can gain substantial benefits from adopting and adapting existing AI tools, even without building the most expensive frontier models themselves. But adaptation requires investment in education, connectivity, reliable electricity, local data, and technical expertise. Without those foundations, the global AI revolution risks reinforcing inequalities it promises to overcome.
The Problem of Digital Dependence
Economic concentration becomes especially consequential when governments and institutions begin relying on AI systems for essential services. Consider a public university using a commercial AI platform for research and teaching, a hospital depending on AI-powered diagnostic assistance, or a small country adopting externally developed systems for public administration. These arrangements can deliver genuine benefits. But they also create questions about continuity, pricing, accountability, and control.
What happens if the provider changes its terms? What if access becomes more expensive? Can the institution transfer its data and applications to another system? Who determines which languages, research priorities, and social needs receive attention? Such questions are increasingly discussed under the concept of technological sovereignty: the ability of institutions and countries to make meaningful choices about the digital systems on which they depend.
Technological sovereignty does not necessarily require every country to manufacture its own chips or develop a national AI model. It can also mean maintaining alternative suppliers, investing in local expertise, adopting interoperable technologies, and preserving the ability to change providers. The essential issue is not complete independence. It is avoiding dependence so deep that meaningful choice disappears.
Can Open AI Models Change the Balance?
One possible counterweight to concentrated corporate power is the growing availability of openly released AI models. Some developers publish model weights that organizations can download, modify, and operate on their own infrastructure, subject to the applicable licenses.
These models can reduce dependence on a single commercial API and enable researchers, businesses, and governments to adapt AI systems to local needs. They also encourage experimentation outside the largest technology companies. But open availability does not eliminate every barrier.
Operating a powerful model may still require expensive hardware, specialized knowledge, electricity, and reliable infrastructure. Some models described as open also impose licensing restrictions or do not disclose their training data and development methods. Furthermore, smaller developers may remain dependent on the same cloud providers and semiconductor manufacturers that dominate the broader industry. Open models can expand participation. They cannot, by themselves, solve the problem of concentrated computing power.
What Governments Can Do
Governments face a difficult balancing act. Excessive restrictions could discourage investment and slow technological development. But allowing essential AI markets to become permanently closed to competition could limit innovation and leave businesses and consumers with fewer choices.
Competition authorities are increasingly examining cloud partnerships, preferential access to computing resources, market concentration, and the ability of customers to switch between providers. Public investment may also play a role.
Universities and independent researchers need affordable computing resources to investigate AI systems without relying entirely on corporate sponsorship. Governments can support shared research infrastructure, technical education, and public-interest applications. International cooperation is equally important. Developing countries may benefit from regional computing facilities, shared research programs, and access to models that can be adapted to local languages and public services.
The objective should not be to prevent successful companies from growing.It should be to ensure that success does not become an insurmountable barrier to future competitors, independent research, or public participation.
Who Will Control the Future?
The history of technology offers numerous examples of industries that began with extraordinary innovation and eventually became dominated by a small number of powerful companies. Artificial intelligence may follow a similar trajectory, but its consequences could be more far-reaching. AI is not simply another consumer product. It is becoming part of the infrastructure through which people learn, communicate, work, conduct research, and make decisions. That makes control over its development an issue of public interest.
A competitive and inclusive AI economy would allow new companies to challenge established leaders, universities to conduct independent research, and countries to develop technologies suited to their own populations. It would also give users and institutions meaningful choices about the systems they adopt. The question is not whether large corporations should be allowed to develop powerful artificial intelligence. Their investment and expertise have contributed enormously to the technology’s progress.
The question is whether the future of intelligence should depend so heavily on the decisions of so few. Artificial intelligence may eventually place extraordinary knowledge within everyone’s reach. But access to intelligence is not the same as power over it. And unless that distinction receives serious attention, the most transformative technology of our time could become another instrument for concentrating the world’s economic and technological power.
Fuentes:
Los datos centrales proceden de investigaciones de la OCDE sobre mercados de IA y Epoch AI sobre concentración de capacidad informática. La investigación de la FTC sobre alianzas empresariales documenta los posibles riesgos competitivos. Los aspectos internacionales se apoyan en UNCTAD y el Banco Mundial